
Orquesta conocimientos de IA para convertirlos en acción

Tendencias
Categories
BEB criminal cases against airlines are built on a false interpretation of leasing
BEB Criminal Cases Against Ukrainian Airlines Based on Misinterpretation of Leasing Payments
The Bureau of Economic Security (BES) has initiated criminal proceedings against several Ukrainian airlines on the premise that payments made for leasing aircraft from non-resident entities constitute royalties. This interpretation, however, stands in direct contradiction to Ukrainian tax legislation, international conventions aimed at avoiding double taxation, and established judicial practice. Legal experts, auditors, and tax consultants have collectively reached this conclusion during a recent roundtable discussion addressing the complexities of aviation leasing taxation, as reported by UNN.
Disputed Taxation Approach and Its Impact on Airlines
The BES contends that Ukrainian carriers should have paid an additional 15% tax on income paid to non-residents, treating aircraft lease payments as royalty payments subject to withholding tax. This stance has adversely affected at least five airlines, including Ukraine International Airlines (MAU), Aviation Company Constanta, Urga, N3Operations, and Skyline. A significant point of contention highlighted by experts is that most of these airlines have already undergone comprehensive tax audits covering the very periods now under BES investigation. According to the State Tax Service, these audits largely cleared the airlines of any violations, with only one audit identifying a misclassification of leasing payments as royalties.
Victoria Kasyan, Deputy Director of the Transfer Pricing Department at the State Tax Service of Ukraine, emphasized that the reclassification of leasing payments as royalties was based solely on the findings of a single audit within the aviation sector. Despite this, law enforcement agencies have revisited the same transactions, applying a new and more stringent interpretation of the law. This has resulted in demands for retroactive payments of the 15% royalty tax covering the past seven years, a move that experts warn could severely undermine the viability of Ukraine’s civil aviation industry.
Legal and International Frameworks Contradict BES Interpretation
Certified auditor and tax consultant Tetiana Shevtsova, a member of the Public Council under the Ministry of Finance, underscored that international conventions on the avoidance of double taxation—cited by law enforcement to justify their position—do not support the automatic classification of aircraft lease payments as royalties. Shevtsova pointed out that even the OECD Model Convention’s commentaries, which the Ukrainian tax authorities typically rely upon for interpreting international agreements, clarify that references to equipment leasing pertain specifically to the transfer of innovative technologies or production processes. Ordinary leasing of vehicles, including airplanes and helicopters, falls outside this scope.
Furthermore, Ukrainian legislation explicitly excludes leasing from the definition of royalties. Lease payments to non-residents are recognized as a distinct category of income under Ukrainian tax law. Shevtsova emphasized that airplanes, containers, and wagons are classified as vehicles rather than equipment, reinforcing the argument that leasing payments should not be treated as royalties. She described the BES’s current interpretation, which equates leasing with the use of intellectual property, as “strained” and called for a thorough review of the issue involving the Ministry of Finance, the State Tax Service, and the expert community.
Risks of Arbitrary Interpretation for Ukraine’s Aviation Sector
The ongoing dispute highlights a broader concern regarding the interpretation of international tax conventions in Ukraine. While international law provides a framework that could benefit the country, arbitrary or inconsistent application of these conventions by law enforcement agencies introduces significant risks. Such practices not only threaten the stability of the aviation sector but also undermine investor confidence and the rule of law in tax administration. The situation calls for coordinated action among government bodies and experts to ensure that taxation policies align with both domestic legislation and international standards.
Etihad and Swissport Extend Global Partnership
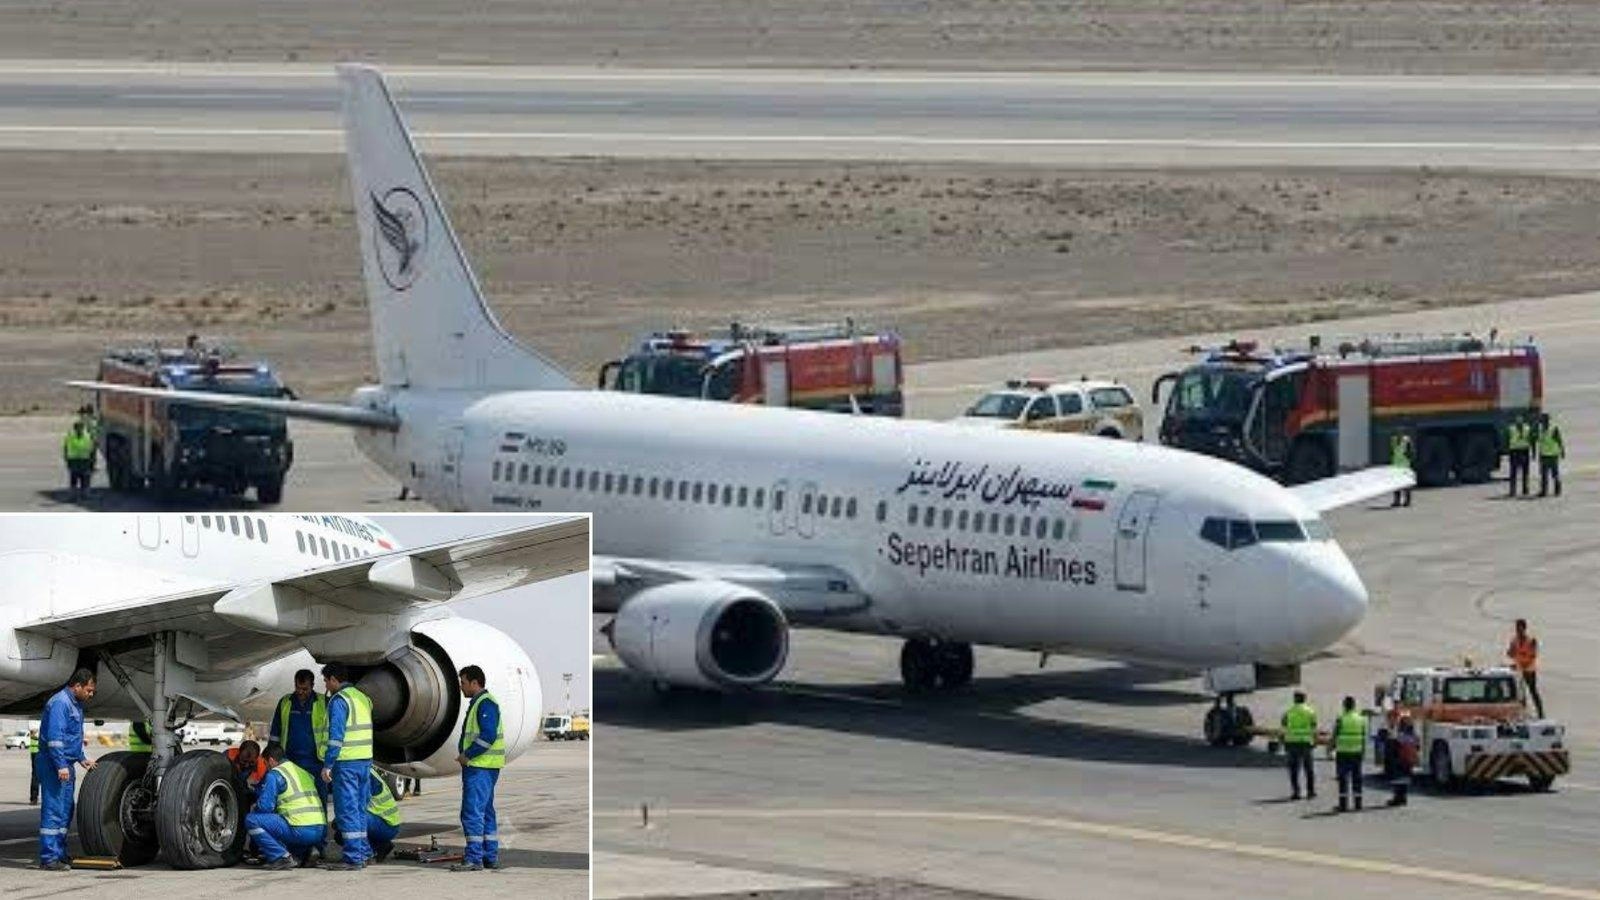
Sepehran Airlines B737 Returns to Mashhad After Tyre and Engine Issues
Etihad Deploys Widebody Fleet to Meet Strong Demand
Korean Air Finalizes $36.2 Billion Deal with Boeing
Australia’s RFDS Queensland Section Orders Six King Air 260Cs
Korean Air Finalizes Order for 103 Boeing Jets and Engines
Embraer E195-E2 Features Distinctive Engine Placement Among Regional Jets
What Passengers Can Expect on Boeing’s New 777X Jet
How Ethiopian Airlines Became Africa’s Leading Carrier Amid Gulf Competition
Joby Aviation Extends Autonomous Flight Capabilities with Cross-Country Tour
